Key Takeaways
- Financial evidence can shape the strength of claims, defenses, settlement positions, and damages arguments.
- Important records may include account statements, loan files, contracts, internal notes, payment histories, and electronic communications.
- A reliable timeline helps separate confirmed events from disputed interpretations.
- Damages calculations should identify their source records, assumptions, and methodology.
- Clear explanations are often more persuasive than large volumes of unorganized financial data.
Banking disputes are often decided by the quality, organization, and interpretation of the financial record. Effective banking litigation support can help legal teams connect account activity, loan documents, communications, and calculations to the issues that actually matter in a case.
Whether the dispute involves a commercial loan, deposit account, guaranty, payment default, collateral issue, or alleged servicing error, broad allegations are rarely enough. The key questions are usually practical: what happened, when it happened, who authorized it, what the records show, and whether a measurable financial loss resulted.
1. Why Financial Evidence Matters
Financial evidence gives a banking dispute a factual foundation. A signed note may establish repayment obligations, but it does not necessarily explain how funds were advanced, how payments were applied, whether a modification occurred, or how a claimed balance was calculated. Those answers may be found across many records.
For example, a disputed commercial loan may involve the note, guaranty, underwriting materials, payment history, appraisal, internal approval records, workout communications, and notices of default. Reviewing those documents together can reveal whether the timeline and claimed loss are consistent with the available evidence.
2. Common Types Of Financial Evidence
Bank Statements And Transaction Records
Statements, deposit records, wire confirmations, canceled checks, ledger entries, and transaction histories can help trace the movement of money. They may establish dates, amounts, account balances, reversals, fees, and the sequence of activity surrounding a disputed event.
Loan And Credit Files
Loan files commonly include applications, credit memoranda, underwriting materials, collateral documents, payment schedules, modification agreements, and collection correspondence. These records can help explain the lender’s decision-making process and the borrower’s obligations.
Contracts, Policies, And Communications
Promissory notes, account agreements, security agreements, guaranties, and amendments provide the contractual framework. Internal policies may offer context for stated procedures, while emails, system notes, and messages can show how participants understood or handled a particular issue.
3. Building A Reliable Financial Timeline
A timeline turns scattered documents into a sequence that a judge, jury, client, or mediator can follow. It should identify important dates, transactions, decisions, communications, account changes, and unresolved questions.
- Organize records by account, loan, party, or transaction.
- Sort documents by date and identify their source.
- Record the event, amount, and related agreement or communication.
- Flag missing records, duplicate documents, and conflicting figures.
- Separate confirmed facts from disputed assertions.
A practical entry might include the date of an alleged payment, the amount shown on a statement, the supporting document, and a question about whether the payment was applied to principal, interest, fees, or another obligation. This format keeps the analysis focused on evidence rather than assumptions.
4. Reviewing Banking Practices And Procedures
Reviewing banking practices requires context. A process that may be routine for one type of credit relationship may not apply to another. The relevant considerations can include the borrower, collateral, loan size, risk profile, contractual terms, market conditions, and the period in which decisions were made.
Common review areas include underwriting steps, approval authority, collateral valuation, payment application, account restrictions, loan modifications, default notices, collection activity, and internal escalation. Written policies can be useful, but they should be compared with evidence of what occurred in the specific matter.
5. Analyzing Financial Losses And Damages
A damages analysis should begin with a clearly stated theory of loss. The calculation should identify the financial position asserted before the disputed conduct, the position afterward, and the basis for any difference. A spreadsheet can summarize the analysis, but it should not replace the underlying records.
Potential categories may include unpaid principal, accrued interest, fees, additional financing costs, reduced asset value, lost income, or recovery expenses. Each claimed amount should be tied to a source document, a stated assumption, and a method that can be reviewed and tested.
6. The Role Of A Financial Expert Witness
A financial professional may serve as a consulting expert, a fact witness, or a testifying expert witness, depending on the engagement and applicable rules. The role may involve reviewing records, testing calculations, identifying missing data, preparing analyses, and explaining complex financial issues in understandable terms.
For testimony, the analysis should be grounded in reliable information and a transparent methodology. The standards governing expert opinions can vary by jurisdiction, and federal cases may consider the framework set out in Rule 702. Useful opinions acknowledge limitations rather than stretching the available evidence beyond what it supports.
7. Common Problems With Financial Evidence
- Incomplete records: Missing statements, servicing notes, or communications can leave key events uncertain.
- Conflicting balances: Different systems or reports may reflect different dates, posting methods, or assumptions.
- Unclear calculations: A claimed amount may be difficult to evaluate when its inputs are not identified.
- Poor source tracking: Figures lose persuasive value when the supporting documents cannot be located quickly.
- Overly technical explanations:Sound financial work can be less effective if nonfinancial readers cannot follow it.
One missing payment record can affect the alleged balance, the interest calculation, the default date, and the total damages. Identifying that gap early may prevent a case team from relying on an incomplete or overstated narrative.
8. A Practical Case Preparation Checklist
- Define the central financial dispute in one or two sentences.
- Identify all relevant parties, accounts, loans, and related entities.
- Collect agreements, statements, ledgers, communications, and supporting reports.
- Create a document index showing date, source, subject, and relevance.
- Build a timeline that links transactions to decisions and communications.
- Recalculate key balances, interest, fees, and claimed losses.
- List open questions and distinguish missing facts from disputed interpretations.
- Test whether an opposing theory could produce a different result.
9. Common Questions
What Financial Evidence Is Most Useful In A Banking Dispute?
The answer depends on the claim, but loan documents, account statements, transaction histories, internal records, communications, and payment evidence are often central.
When Should Records Be Reviewed?
Early review can identify missing documents, calculation issues, and discovery priorities before positions become difficult to revise.
What Makes A Financial Analysis Persuasive?
Accurate source records, clear assumptions, reproducible calculations, and plain-language explanations make an analysis easier to evaluate.
10. Conclusion
Financial evidence is most valuable when it is organized, tested, and tied directly to the questions in dispute. A disciplined review can clarify the facts, identify weaknesses in competing positions, and provide a stronger basis for litigation strategy, settlement discussions, and courtroom presentation.
- Financial Evidence In Banking Litigation: A Practical Guide
- What Buyers Should Check Before Buying a Coastal Home in Newport Beach, CA
- How to Build a Men’s Shirt Rotation That Works All Year
- A Practical Checklist for Buying an Investment Property in Northwest Florida
- A Checklist for Choosing a Tooth Replacement Plan in Rapid City, SD
Key Takeaways Financial evidence can shape the strength of claims, [...]
Key Takeaways A coastal home should support both your lifestyle [...]
A reliable shirt rotation makes getting dressed easier because each [...]
Buying an investment property in Destin, Fort Walton Beach, Niceville, [...]
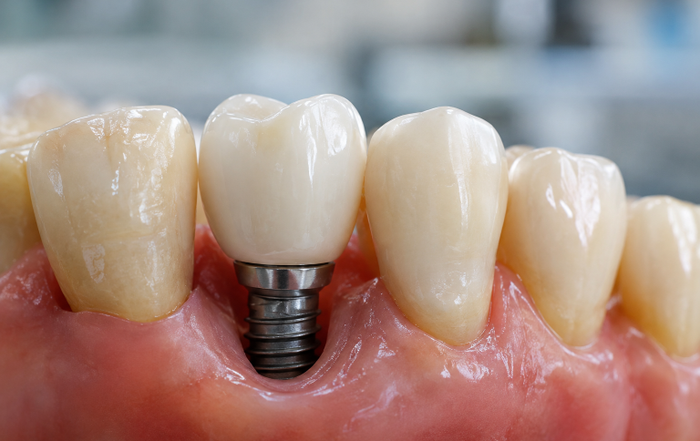
Replacing a missing tooth is not simply a matter of [...]
Key Takeaways Shibby RV Living is located in Woodruff, South [...]
How Real Reviews Can Influence Digital Marketing Decisions
How to Build a Winning Team in Today’s Competitive Job Market
The Role of Industrial Casters in Enhancing Workplace Efficiency and Safety